
Commission paid to a partner is a service you buy. Two taxes can apply, and the payout works out both.
GST
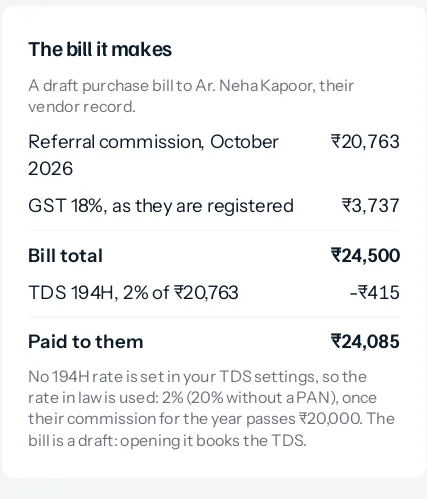
A partner registered for GST charges it on their commission. If the vendor linked to the partner has a GSTIN, the payout adds GST at 18% to the bill. One without a GSTIN is billed without GST. The bill works out whether that is CGST and SGST or IGST from the vendor’s state, as any purchase bill does.
TDS under section 194H
Section 194H of the Income Tax Act asks the business paying commission to deduct tax from it. The payout takes the rate from, in this order:
- The vendor’s own record, when its TDS section is 194H and it has a rate.
- Your 194H section in Settings, Taxes, if you have one: its rate, or its rate without a PAN when the vendor has none.
- The rate in law: 2%, or 20% for a partner with no PAN on file.
The page says which it used. TDS is on the commission before GST.
The ₹20,000 threshold
No TDS is due until a partner’s commission for the April to March year passes ₹20,000, or the threshold in your own 194H section. Until then, each payout says “Within the year’s TDS threshold.” From the month it passes, TDS is taken on that month’s commission and every month after.
In the month it passes, TDS is also due on the earlier months’ commission, and that month’s bill takes it at the same rate: it deducts on its own commission and on the earlier months’ commission billed without TDS. The payout says so, for example “the bill also takes ₹300 of TDS on the earlier months’ ₹15,000”, and the TDS register shows the whole base, ₹500 on ₹25,000, under 194H in that month.
Every month worked out in the year counts towards the threshold, billed or not, so months billed together still cross it.
An example
Studio Ochre earns ₹15,000 in April and ₹10,000 in May at 2%. April has no TDS. May’s bill takes ₹500: ₹200 on its own ₹10,000 and ₹300 on April’s ₹15,000. From June, each month takes 2%.
Rates and thresholds change with each budget. Keep your 194H section in Settings, Taxes up to date, and check with your accountant if unsure.
Where the PAN and GSTIN come from
Both are read from the vendor linked to the partner, the same record their bill goes to. Fill in the vendor’s PAN before the first payout that takes TDS, or the higher rate for no PAN applies: a partner with no PAN is still billed, with TDS at 20% under section 206AA.
Something missing or wrong here? Tell us. A question that needed asking usually means a page that needed writing.